Taxable period
The tax year for company tax return is starting from 1 July through 30 June. However, tax authorities have powers to allow a special year-end.
ALSO READ: Annual Income tax return filing last date December 31 2020 for companies
Company tax returns
All companies are required to file an income tax return each year by 31 December. For the preceding financial year (1 July through 30 June) by accounting for business income on an accrual basis. If the special year granted by the tax authorities ends between 1 July and 31 December, then the tax return is required to be filed by 30 September following the year-end.
Persons subject to final tax regime were required to file a statement prescribed in the law in lieu of income tax return. The concept of statement in lieu of return has now been omitted with such persons now required to file a return income. The FBR is to prescribe returns for different classes of income or persons including those covered by final tax regime. Tax authorities can require a person whose name is not appearing in the ATL to file income tax return for any of the last ten years.
Filing of a revised return requires prior approval of the Commissioner of income tax. With subject to certain limitations and conditions. The Commissioner of income tax is also empowered to grant approval for revision of return due to omission or wrong statement. Now, time limit for notifying annual income tax return form under the Income tax Ordinance, 2001 has also been introduced.
ALSO READ: File tax return or pay penalty for tax year 2020: FBR started issuing tax notices
Payment of due taxes
Companies have to pay advance tax under section 147 of the Income Tax Ordinance, 2001 on the basis of tax liability of the immediately preceding tax year in respect of their income (excluding final tax regime income sources). The advance tax is to be paid after adjusting the withholding / advances taxes (excluding relating to Final tax regime).
Advance tax, payable in four quarterly installments on or before 25 September, 25 December, 25 March, and 15 June in each financial year. Adjustment for advance tax paid under section 147 in a tax year, allowed against tax liability of that year. In case of banking companies, such quarterly advance income tax is payable on a monthly basis.
The rest of the tax liability payable at the time of filing the return of income under section 137 of Income Tax Ordinance, 2001 as admitted income tax. Advance income tax and withholding income tax are adjustable against the tax payable with the return of income. FBR now empowered to explain a procedure for filing and calculating of turnover for the quarter through an automated system.
Process of tax audit
The Federal Board of Revenue (FBR) authorized to prescribe criteria for selection of audit of taxpayers who have filed their income tax returns for a tax year. Cases selection through computer ballot separately for income tax, sales tax, and federal excise duty. Currently, composite tax audit also introduced. The income tax returns then scrutinized by FBR, and related documents and information noticed to provide. After examination of returns and related information show-cause notices circulated. In case of disagreement with tax authorities, the taxpayer has the right to submit appeals before appellate forums.
A specific procedure has been provided for ‘automated initial scrutiny’ by FBR system within six months of filing of income tax return for any arithmetical & clerical errors. In case no such adjustment made within six months by the system, then there will be acceptance of the taxpayer’s declared version.
An ‘agreed assessment’ concept introduced also. A taxpayer if wants to settle a case may submit application of settlement before the committee. In case of agreement, taxpayer can deposit the tax due after passing an amendment order. Taxpayer in this case shall lose his right to appeal. This is not available in case of involvement of concealment of income or where the interpretation of question of law is involved having effect on other cases.
The tax authority has right of access to taxpayers’ premises, place, accounts, documents or computer, if required, in case of any proceedings. Tax officers allowed to conduct audit proceedings through video links or any other electronic medium.
ALSO READ: FBR allowed to taxpayers to file settlement application for agreed assessment
Law of limitations
An audit of the income tax return filed by a company, FBR can initiate audit within five years of the end of the financial year in which the income tax return is filed.
Non resident company can apply for advance rulings
A non-resident company which has no operations in Pakistan through a permanent establishment (PE). It can apply to FBR to issue an advance ruling. It will give the FBR’s stance regarding application of the income tax provisions. The tax ruling issued, bounds to FBR.

Intention of Federal board of revenue (FBR)
The Tax authorities have mainly intention on the following topics:
Withholding taxes.
Issue of Transfer pricing.
Expenditure & business Relationship.
Advance tax payments.
Payment of due taxes within the time.
Audit of income tax returns filed.
Tax compliance by taxpayers.
Recovery of tax arrears.
Source | Income Tax Return | Company Income Tax Return | How to Become Active tax filer in FBR | Extension in Date of Income Tax Return Filing | Tax Audits | Tax Assessment |
LATEST POSTS
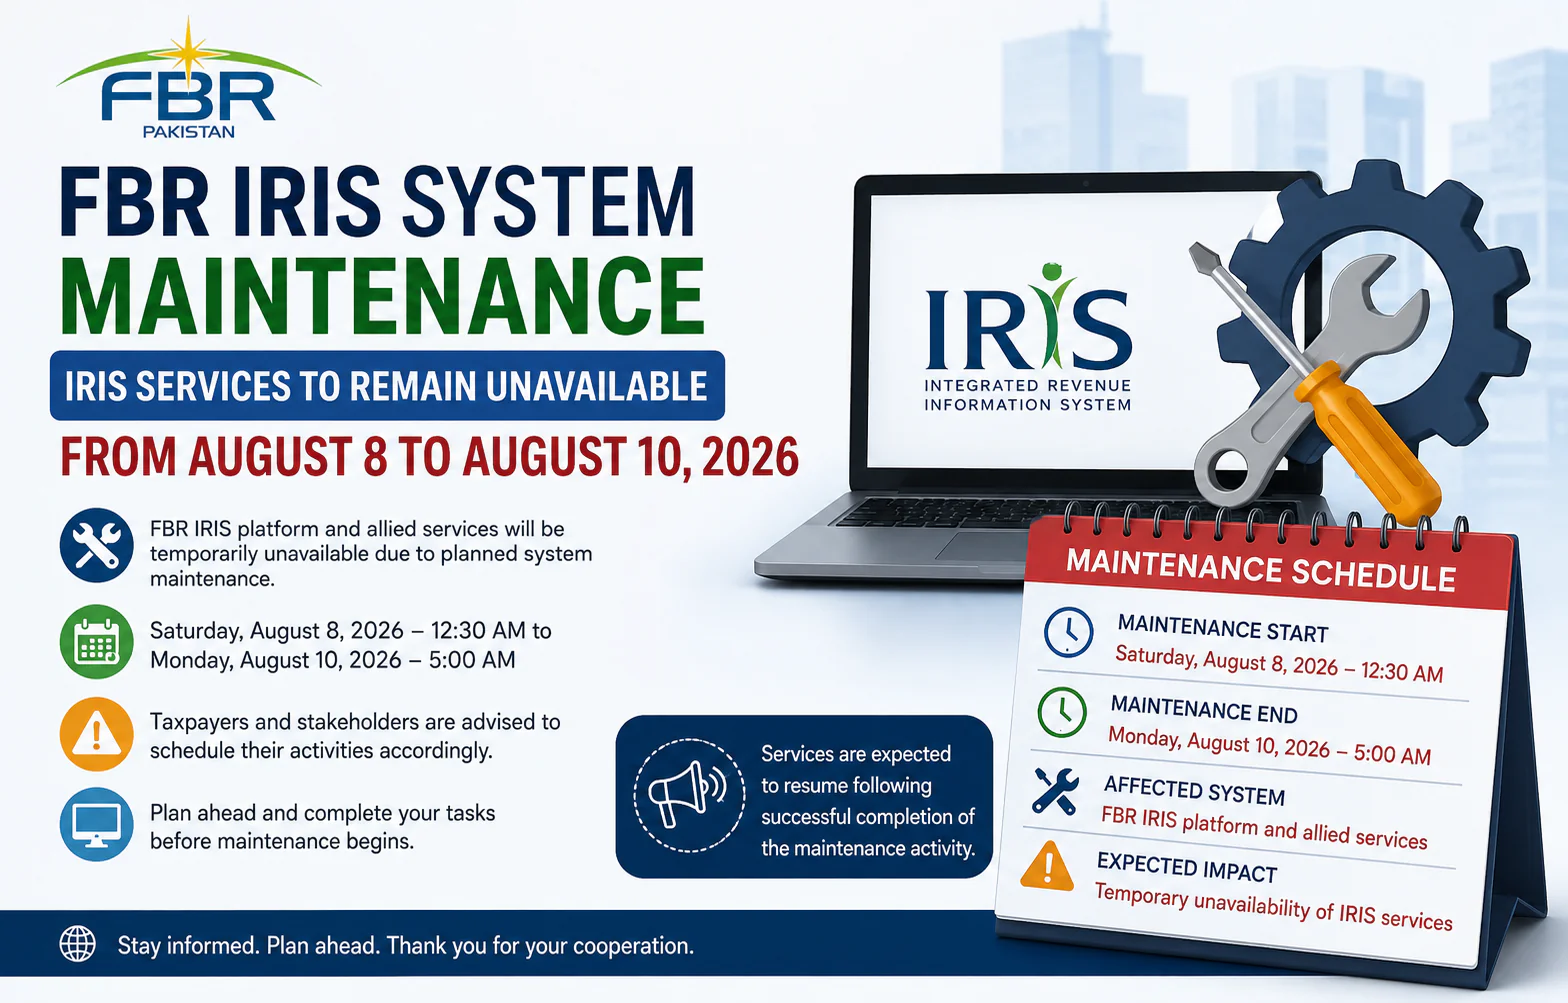
- FBR IRIS System Maintenance: Services to Remain Unavailable from August 8 to August 10, 2026
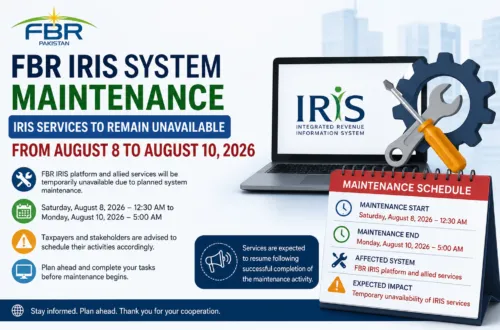
 FBR IRIS Maintenance Schedule August 2026: IRIS Services Temporarily Unavailable The Federal Board of Revenue (FBR) today announced on his website that a planned system maintenance activity for its IRIS platform and allied services scheduled to begin at 12:30 AM on Saturday, August 8, 2026, and expected to continue until 5:00 AM on Monday, August 10, 2026. FBR IRIS Maintenance Schedule The announced maintenance window is as follows: Particular Details Maintenance Start Saturday, August 8, 2026 – 12:30 AM Maintenance End Monday, August 10, 2026 – 5:00 AM Affected System FBR IRIS platform and allied services Expected Impact Temporary unavailability of IRIS services In notice FBR has advised taxpayers and stakeholders to schedule their activities accordingly. IRIS and Allied Services Will Be Temporarily Unavailable During the maintenance period, the IRIS platform and its allied services will remain temporarily unavailable. All users may not be able to access the system. What Should Taxpayers Do Now? Taxpayers, businesses and tax practitioners should take the maintenance schedule into account when planning their online tax activities. Users of FBR IRIS system may reschedule their activities and can focus on preparation of tax working papers and schedule submission of tax returns and related activities after IRIS will available on Monday morning. When Will FBR IRIS Services Resume? According to the official announcement, the scheduled maintenance expected to end at 5:00 AM on Monday, August 10, 2026. Services expected to resume following successful completion of the maintenance activity. TAGS How to Check ATL Status with FBR | How to Download Taxpayer Registration Certificate FBR Online | Taxpayer Profile Inquiry Online FBR | How to Become an Active Tax Filer in Pakistan | FBR Iris Registration | How to File Income Tax Return in Pakistan | FBR Income Tax Return | FBR NTN Verification | FBR Taxpayer Registration | Active Taxpayer List (ATL) | FBR Tax Updates | Income Tax Return Filing | Pakistan Tax Return | FBR Online Services
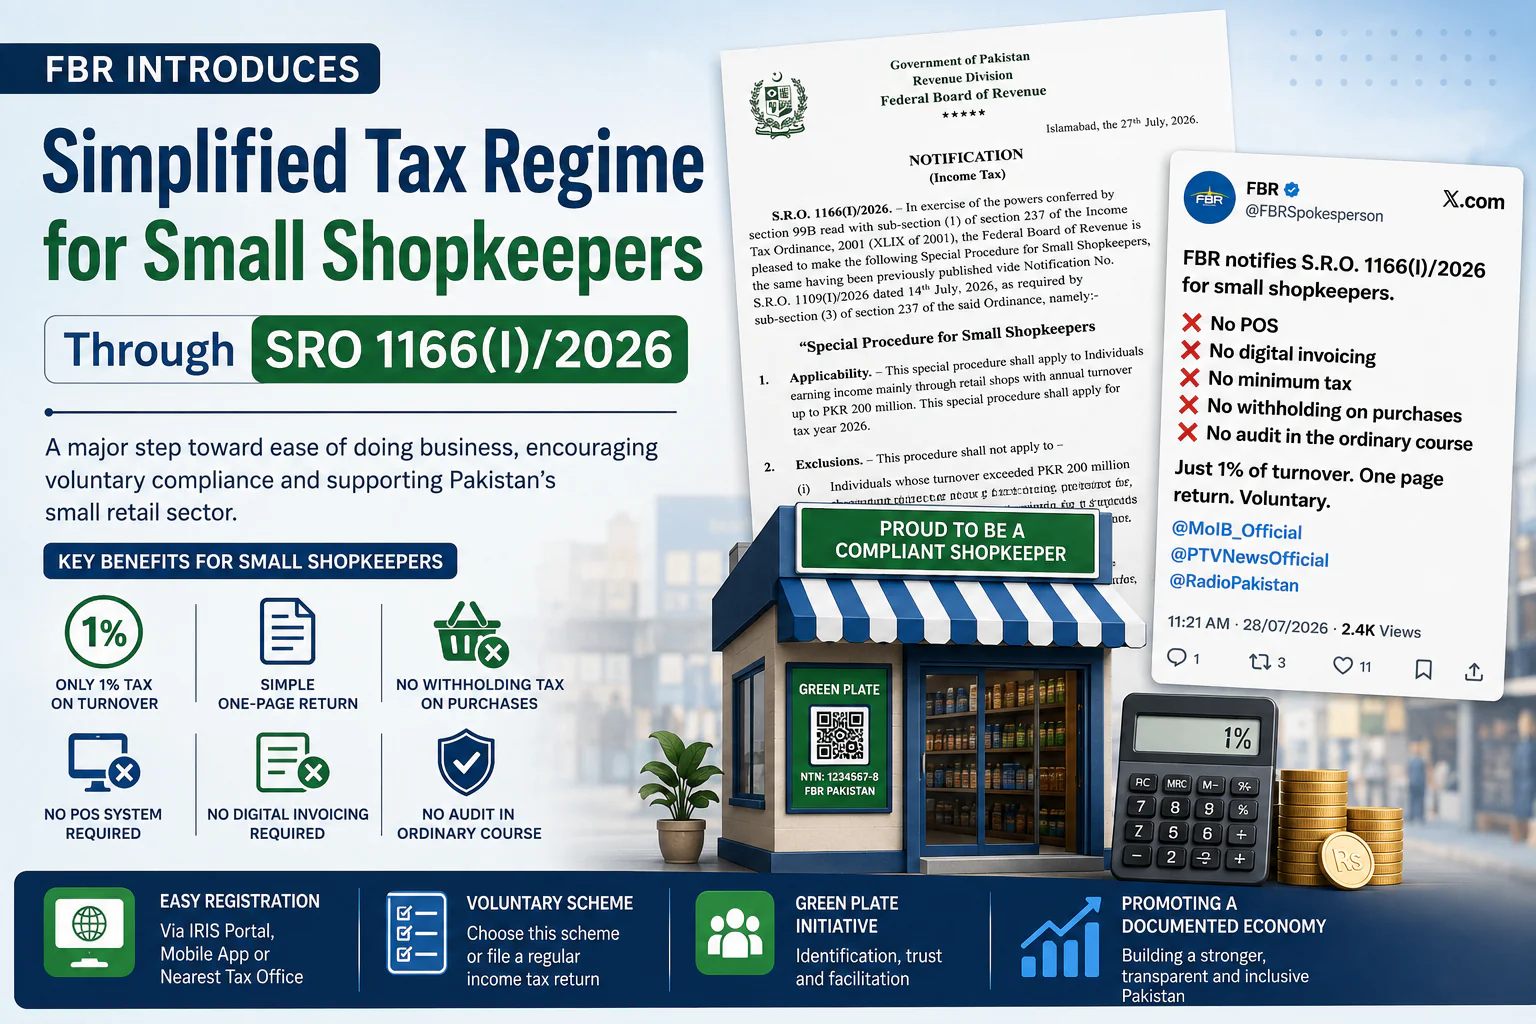
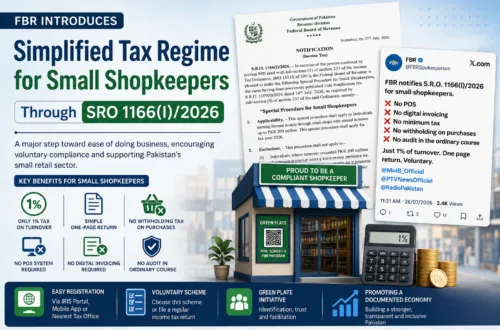
- FBR Introduces Simplified Tax Regime for Small Shopkeepers Through SRO 1166(I)/2026FBR Launches Special Tax Scheme for Small Shopkeepers Under SRO 1166(I)/2026 A Major Step Toward Ease of Doing Business for Pakistan’s Small Retail Sector Small shopkeepers and retailers are the backbone of Pakistan’s economy. This sector from grocery stores and clothing outlets to electronics and household goods retailers, millions of small businesses creating employment opportunities and sharing in economic activity in the country. Small retailers always feel the tax system complex, difficult to comply with. In this regard, the Federal Board of Revenue (FBR) has recently introduced a new Special Procedure for Small Shopkeepers through SRO 1166(I)/2026. It will simplify tax compliance, increase in no of taxpayers, and business-friendly environment for small retailers across the country. What is SRO 1166(I)/2026? On July 27, 2026, the Federal Board of Revenue issued SRO 1166(I)/2026 under Section 99B read with Section 237 of the Income Tax Ordinance, 2001. The notification introduces a special tax procedure applicable to eligible small shopkeepers for Tax Year 2026. The main purpose of this scheme is to provide a simple and practical tax system that allows small retailers to fulfill their tax obligations. Who Can Benefit from This Scheme? The special procedure is designed for individual shopkeepers whose annual turnover does not exceed PKR 200 million. The scheme will target small retailers operating a single retail shop. Who Is Not Eligible? The special procedure does not apply to: It is a Completely Voluntary Scheme This is totally A voluntary scheme. Eligible shopkeepers are free to choose between: What is Tax Rate: Just 1% of Turnover Under this scheme, shopkeepers will pay tax at the rate of 1% of gross turnover. This will simplify tax calculations, adjustments, and assessments. Shopkeepers can now easily compute their tax liability based on their total annual turnover. No Need of POS and Digital Invoicing Requirements Under SRO 1166(I)/2026: No Withholding Tax Requirements Normally, are required to withhold taxes on specific purchases under tax law of Pakistan. But under this SRO there is no need to deduct income tax. No Minimum Tax Under Section 113 It also gives relief from the minimum tax provisions under section 113. Shopkeepers under this scheme will not be subject to: Minimum Tax Requirement Under FBR’s Special Procedure for Small Shopkeepers Under FBR SRO 1166(I)/2026, shopkeepers must pay a minimum tax of PKR 25,000 along with their income tax return, regardless of withholding taxes already deducted. The payable tax will be the higher of net tax liability after adjustments or PKR 25,000. Simplified Tax Return Filing For this purpose the FBR has introduced a simplified one-page tax return designed for shopkeepers participating in the scheme. The return will require basic information such as: Importantly, the form will be made available in Urdu and regional languages. Easy Registration Process Eligible shopkeepers have option to register themselves through: Reduced Audit Exposure According to the notification, shopkeepers opting into the scheme will generally not be subject to audit in the ordinary course of business. However, FBR can take action in limited circumstances, including: Introduction of the “Green Plate” Scheme has introduced Compliant Shopkeeper Plate, commonly referred to as the “Green Plate.” Shopkeepers under this scheme will receive a plate consisting: Shopkeeper will place Green Plate prominently outside the business premises. Moreover, tax officials normally will not enter shopkeepers businesses regarding tax matters when the shopkeeper has Green plate displayed. Frequently Asked Questions about SRO 1166 Tags How to Register for NTN in Pakistan | Complete Guide to FBR IRIS Portal | How to File Income Tax Return in Pakistan | Benefits of Becoming an Active Taxpayer | Difference Between Filer and Non-Filer | FBR POS Integration Explained | Digital Invoicing System in Pakistan
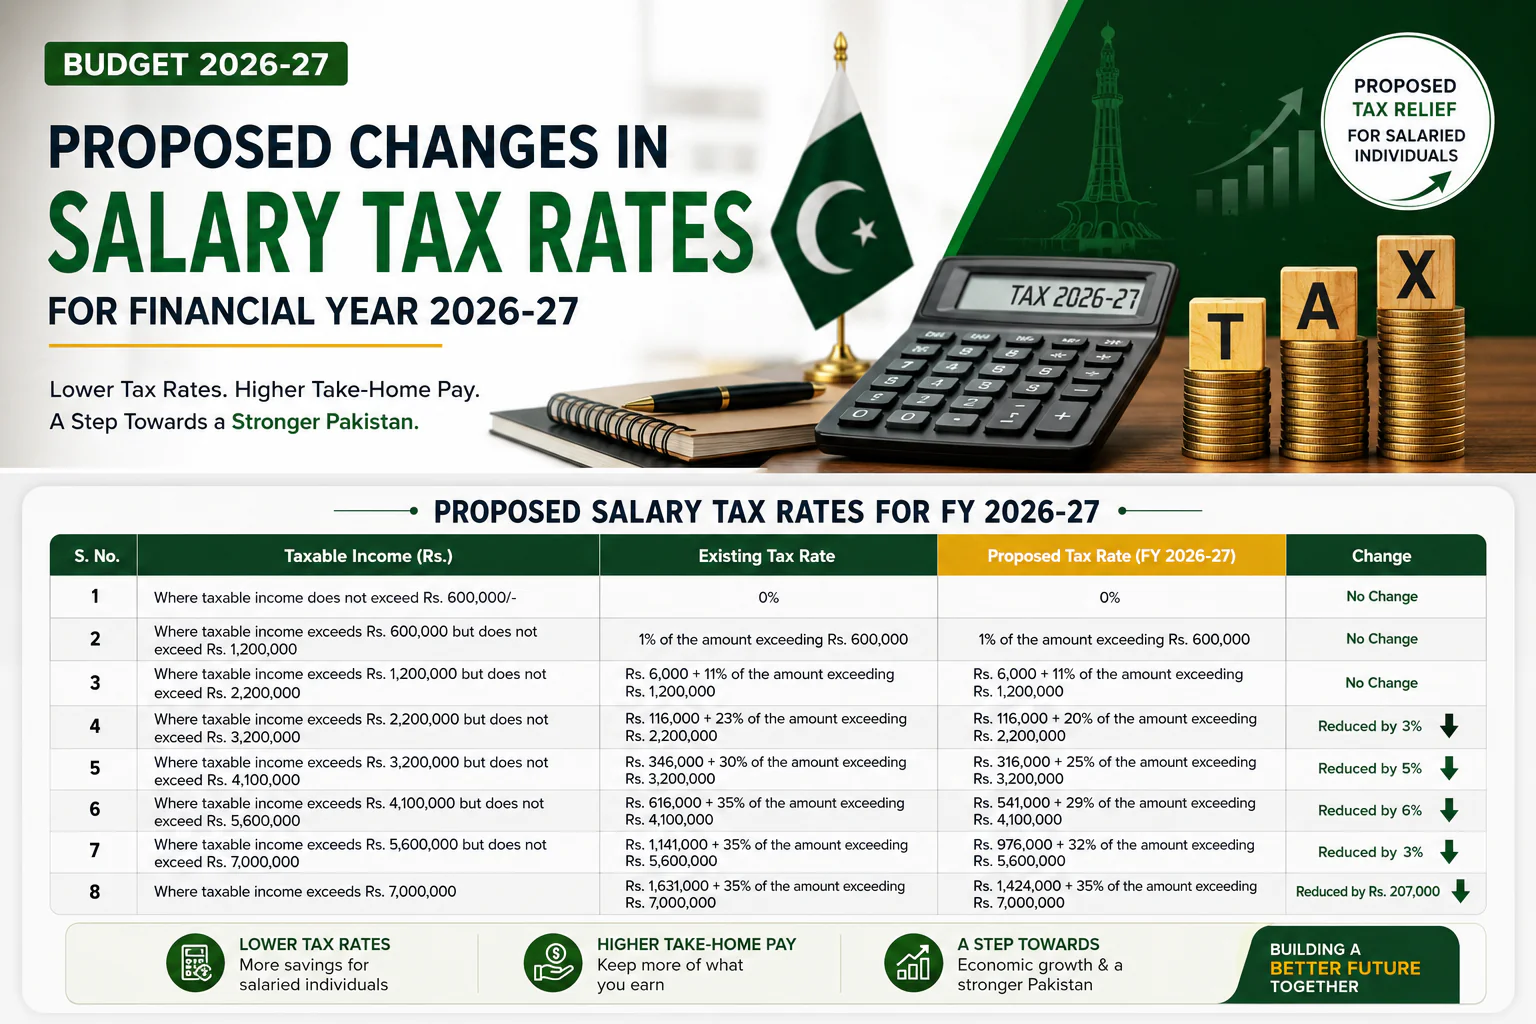
- Pakistan Budget 2026-27: Proposed Salary Tax Rates for Salaried IndividualsProposed Salary Tax Rates for Salaried Individuals in Pakistan Budget 2026-27 The Finance Bill for the 2026‑27 budget proposes a reduction in income tax rates for salaried individuals. Most salaried taxpayers above Rs. 2.2 million in annual taxable income will enjoy a reduction in their tax liability. Here is the proposed slabs, existing salary tax rates, and how much salaried individuals can save once the changes in tax rates take effect. Proposed vs. Existing Salary Tax Rates for FY 2026‑27 S.No Taxable Income Existing Tax Rate Proposed Tax Rate 1 Up to Rs. 600,000 0% 0% 2 Rs. 600,000 – Rs. 1,200,000 1% of amount exceeding Rs. 600,000 1% of amount exceeding Rs. 600,000 3 Rs. 1,200,000 – Rs. 2,200,000 Rs. 6,000 + 11% of amount exceeding Rs. 1,200,000 Rs. 6,000 + 11% of amount exceeding Rs. 1,200,000 4 Rs. 2,200,000 – Rs. 3,200,000 Rs. 116,000 + 23% of amount exceeding Rs. 2,200,000 Rs. 116,000 + 20% of amount exceeding Rs. 2,200,000 5 Rs. 3,200,000 – Rs. 4,100,000 Rs. 346,000 + 30% of amount exceeding Rs. 3,200,000 Rs. 316,000 + 25% of amount exceeding Rs. 3,200,000 6 Rs. 4,100,000 – Rs. 5,600,000 Rs. 616,000 + 35% of amount exceeding Rs. 4,100,000 Rs. 541,000 + 29% of amount exceeding Rs. 4,100,000 7 Rs. 5,600,000 – Rs. 7,000,000 Rs. 1,141,000 + 35% of amount exceeding Rs. 5,600,000 Rs. 976,000 + 32% of amount exceeding Rs. 5,600,000 8 Above Rs. 7,000,000 Rs. 1,631,000 + 35% of amount exceeding Rs. 7,000,000 Rs. 1,424,000 + 35% of amount exceeding Rs. 7,000,000 Who Benefits the Most From the Proposed Salary Tax Slabs? The first two taxable slabs (income up to Rs. 2.2 million) are unchanged, means initial salaried tax slabs won’t see any difference. The change starts from slab 4 onward up to slab no 7. How to Calculate Your Tax Under the New Slabs To calculate your annual tax liability of salary income, you have to identify which slab your taxable salary income falls into. Then apply the formula for that slab: the fixed amount of salary tax plus the stated percentage of salary tax rate of that slab multiply by the income exceeding the slab’s lower threshold. For example, someone earning Rs. 4,500,000 falls in slab 6: Rs. 541,000 + 29% of (Rs. 4,500,000 − Rs. 4,100,000) = Rs. 541,000 + Rs. 116,000 = Rs. 657,000. Additional Tax Surcharge Removed Government of Pakistan has also proposed in the budget 2026-2027 removal of tax surcharge @9% on salary income if it is above than Rs 10 Million Rupees per annum. It is in addition to salary tax rates reductions proposed in the budget. FAQs Section TAGS A step-by-step guide to filing an income tax return | How to compute monthly withholding tax from salary | Budget 2026-27 | Salary Tax Slabs | Income Tax Rates | Finance Bill 2026-27 | Tax Calculator | Salaried Individuals Tax | Income Tax Ordinance | FBR Tax Slabs | Tax Relief | Withholding Tax | Salary Tax Rates 2026-27 | New Tax Slabs Pakistan | Income Tax Calculation Guide | Budget Tax Changes |
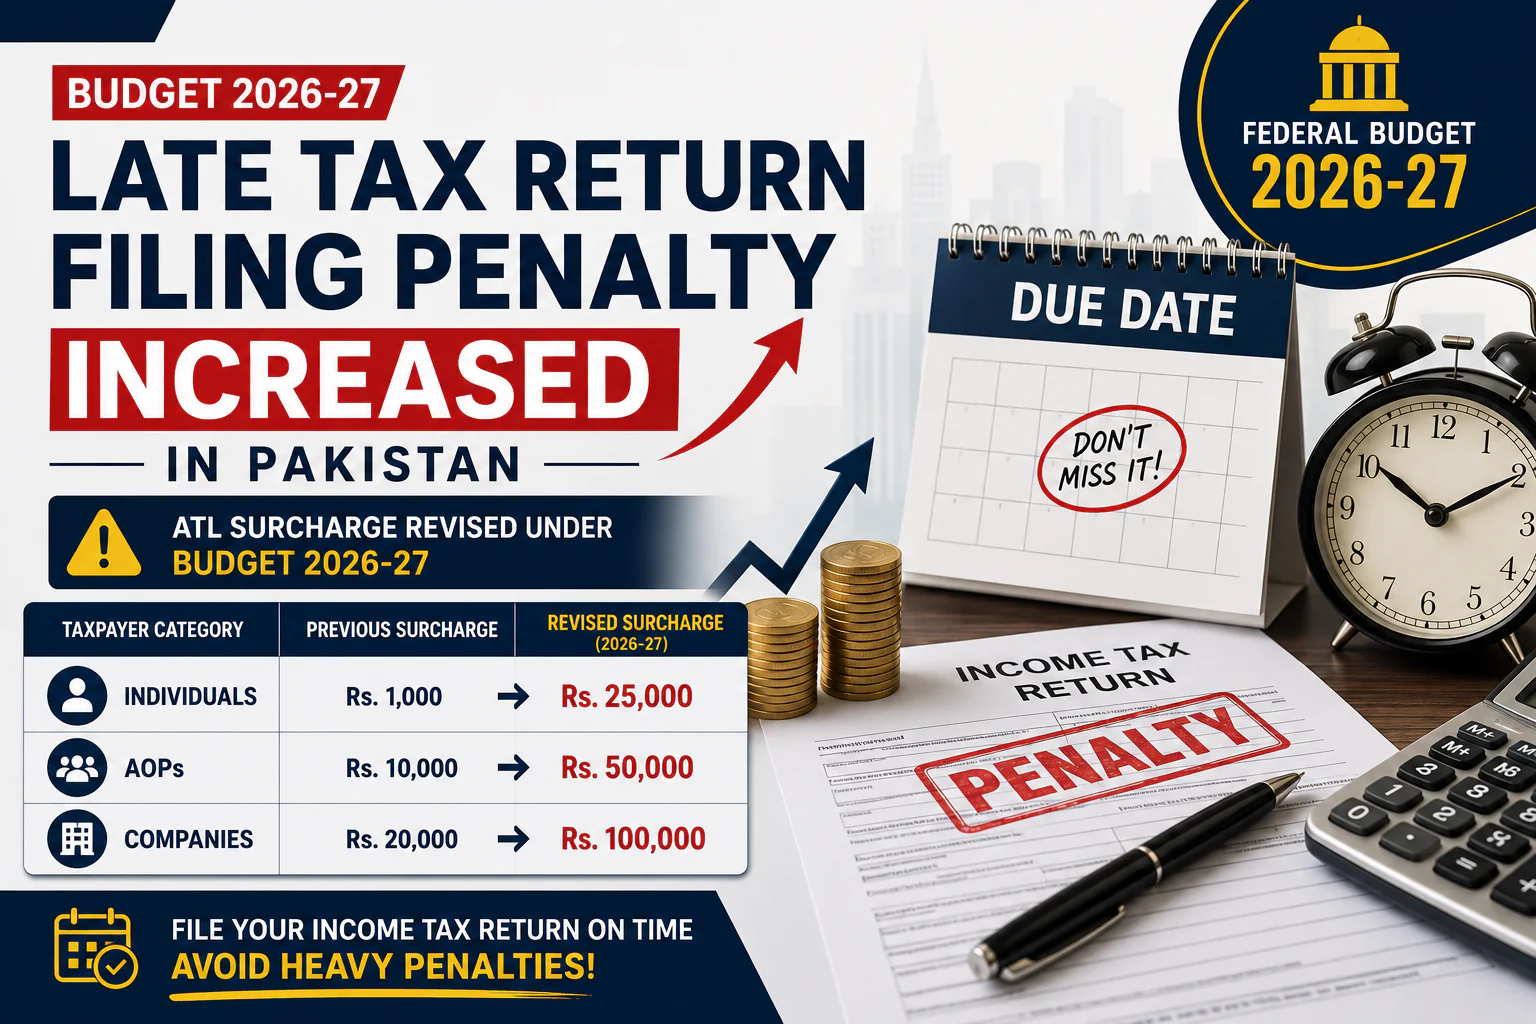
- Budget 2026-27: Government Proposes Massive Increase in Late Tax Return Filing PenaltiesLate Tax Return Filing Penalty Increased in Pakistan Under Budget 2026-27 The Federal Budget 2026–27 has proposed a major increase in the late tax return filing penalties (ATL surcharge) imposed on taxpayers (individuals, AOPs and Companies) who file their income tax returns after the due date. Through an amendment to Section 182A(1)(a) of the Income Tax Ordinance, 2001, the Federal Government has revised the ATL (Active Taxpayers List) surcharge as follows: Taxpayer Category Previous Surcharge Proposed Surcharge Individuals Rs. 1,000 Rs. 25,000 AOPs Rs. 10,000 Rs. 50,000 Companies Rs. 20,000 Rs. 100,000 The proposed amendment is to encourage timely filing of income tax returns and increase tax compliance across the country. The increase is particularly significant for individuals, where the surcharge raised twenty-five times from Rs. 1,000 to Rs. 25,000. Similarly, companies may face a surcharge of Rs. 100,000 for late filing, compared to the previous amount of Rs. 20,000. Now, taxpayers are advised to file their annual income tax returns within the prescribed due dates to avoid heavy penalties and maintain their status on the Active Taxpayers List (ATL) with FBR. How to File Income Tax Return in Pakistan | Benefits of Being an Active Taxpayer | ATL Status Check Online | FBR Iris Registration Guide | Income Tax Return Due Dates in Pakistan | Penalties for Non-Filers in Pakistan | Budget 2026-27 Highlights | Income Tax Rates in Pakistan 2026
- Pakistan Budget 2026-27 to Be Presented Today in National AssemblyPakistan Budget 2026-27 to Be Announced Today Islamabad, June 12, 2026: The Federal Government is scheduled to present the Pakistan Budget 2026-27 in the National Assembly today. Finance Minister Muhammad Aurangzeb will present the federal budget proposals for the upcoming fiscal year 2026-2027. He will unveil it after approval by the Federal Cabinet. The National Assembly session for the budget presentation is expected to begin at 3:00 PM. The budget is expected on the government’s revenue targets, expenditure plans, taxation measures, and key economic priorities for FY 2026-27. Businesses, taxpayers, investors, and salaried individuals all over the Pakistan are keenly watching today’s budget announcement for any changes in taxes, salaries, pensions, and other fiscal measures. Tax.net.pk will provide live updates, budget highlights, and detailed analysis immediately after the budget speech. Tags Federal Budget Pakistan | Income Tax Rates in Pakistan | FBR Tax Updates | Salary Tax Calculator Pakistan | Withholding Tax Rates in Pakistan | Prize Bond Draw Schedule 2026 | Petrol Prices in Pakistan | Pakistan Economic Updates | Tax News Pakistan | Budget 2026-27 Highlights
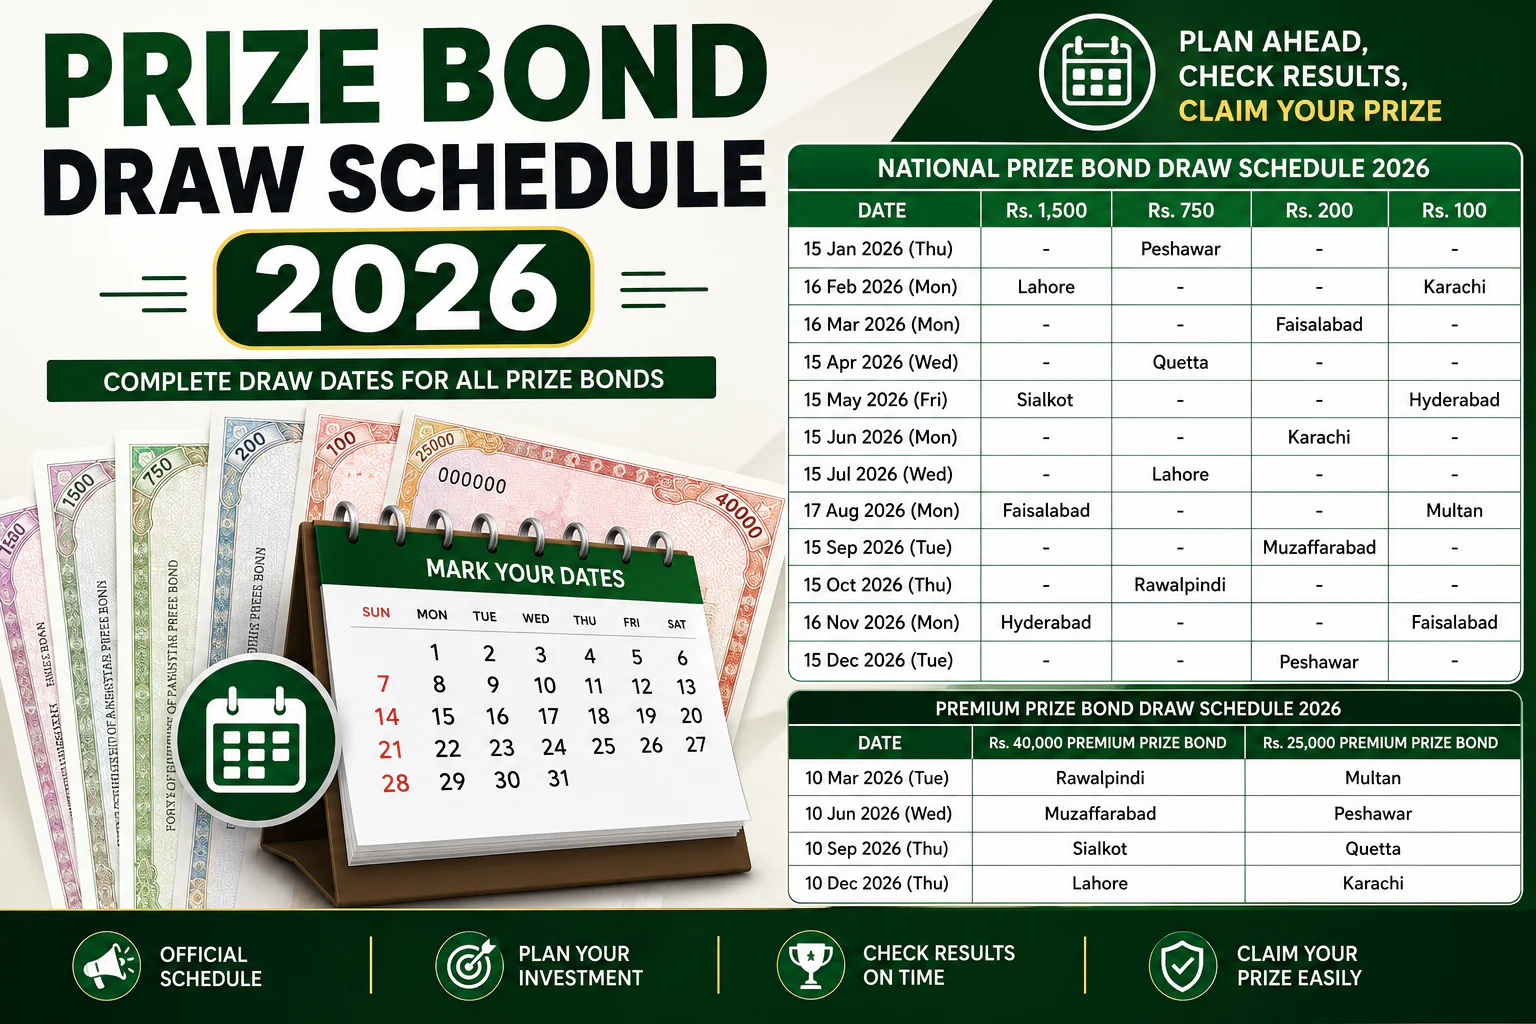
- Prize Bond Draw Schedule 2026 Pakistan – Complete Draw Dates ListPrize Bond Draw Schedule 2026 In Pakistan, prize bonds is very popular investment among the people. People like to invest in this mode of investment because it’s easy to invest, encash, backed by the Government of Pakistan, and profit is also paid on the premium prize bonds. Knowing prize bonds draw dates in advance is very important because you never miss a draw result, stay updated with official announcements, easy to manage, and timely prize money process, peace of mind. Here schedule for the year starting from January 2026 to December 2026 is given. Such schedule is for denominations of: Prize bond schedule for 2026 is also given here for premium prize bonds of: Prize Bond Draw Schedule 2026 Here prize bond draw schedule for 2026 is given for regular type of prize bonds which is not issued in name of investor. Any body can purchase it and invest easily. Schedule is for prize bonds for denominations of Rs 1500, Rs 750, Rs 200, and Rs 100. Date Rs. 1,500 Rs. 750 Rs. 200 Rs. 100 15 January 2026 (Thursday) – Peshawar – – 16 February 2026 (Monday) Lahore – – Karachi 16 March 2026 (Monday) – – Faisalabad – 15 April 2026 (Wednesday) – Quetta – – 15 May 2026 (Friday) Sialkot – – Hyderabad 15 June 2026 (Monday) – – Karachi – 15 July 2026 (Wednesday) – Lahore – – 17 August 2026 (Monday) Faisalabad – – Multan 15 September 2026 (Tuesday) – – Muzaffarabad – 15 October 2026 (Thursday) – Rawalpindi – – 16 November 2026 (Monday) Hyderabad – – Faisalabad 15 December 2026 (Tuesday) – – Peshawar – Premium Prize Bond Draw Schedule 2026 This premium prize bonds schedule is for denominations of Rs 40,000 and Rs 25,000. Draw of premium prize bonds is held quarterly. This type of prize bond is issued in the name of investor. It has benefits like, it is very secure, no risk of theft, profit on investment, and easy to manage. Draw of Premium prize bonds is held quarterly in the following months: Date Rs. 40,000 Premium Prize Bond Rs. 25,000 Premium Prize Bond 10 March 2026 (Tuesday) Rawalpindi Multan 10 June 2026 (Wednesday) Muzaffarabad Peshawar 10 September 2026 (Thursday) Sialkot Quetta 10 December 2026 (Thursday) Lahore Karachi How to Check Latest Prize Bonds Draw Result Online Prize Bond List Online check through: Call to Action If you need help with NTN registration, income tax return filing, ATL status, or FBR matters? You may please Contact Global Tax Consultants for professional tax advisory and compliance services across Pakistan. 💬 WhatsApp Chat 📞 Call Now